Forecasting Volatility Dynamics Using Machine Learning in Live Dealer Gaming Environments
Written by Katja Simon · Jul 7, 2026
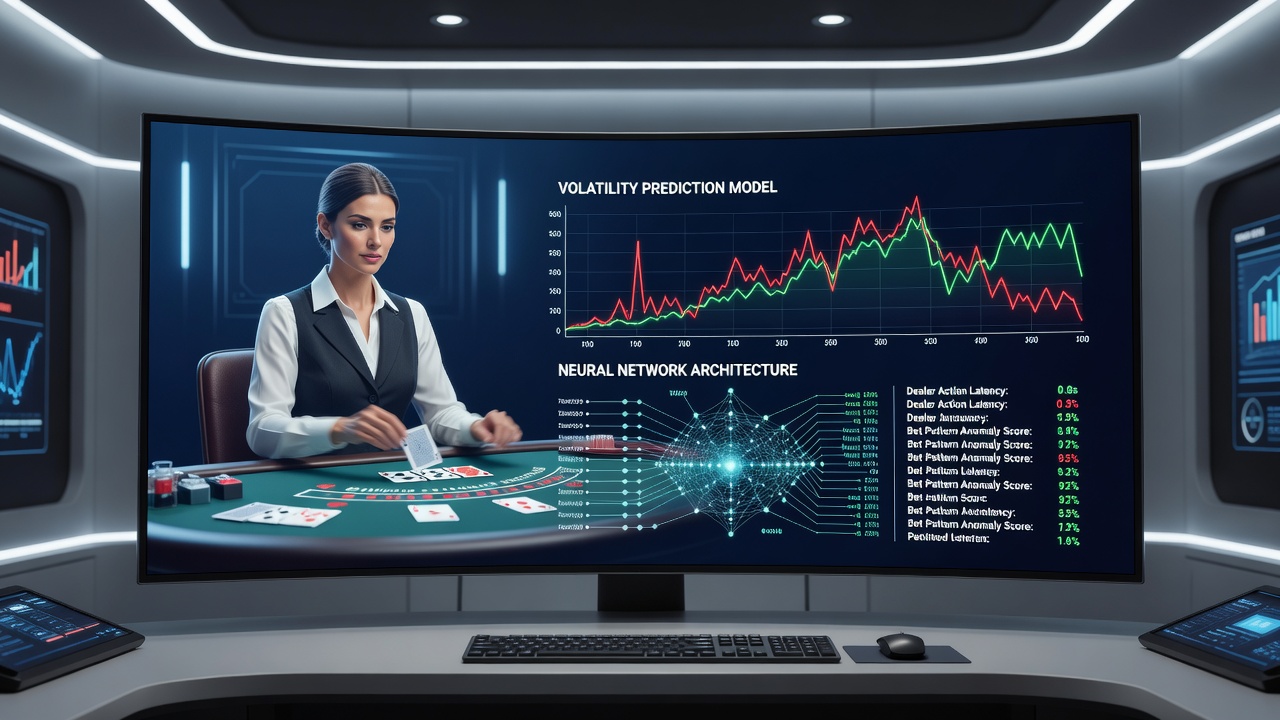
Forecasting Volatility Dynamics Using Machine Learning in Live Dealer Gaming Environments
Live dealer game environments generate continuous streams of data from table interactions, player decisions, and dealer actions that create measurable volatility patterns. Machine learning models process these inputs to identify potential shifts before they fully develop across blackjack, roulette, and baccarat sessions.
Operators collect timestamped records of bet sizes, card distributions, and payout sequences while regulatory frameworks in multiple jurisdictions require transparent data handling. Models such as long short-term memory networks and gradient boosting machines analyze sequences to estimate changes in outcome variance during active play periods.
Data Inputs Driving Predictive Models
Real-time feeds include wager amounts, hand outcomes, and dealer shuffle intervals along with environmental signals like table occupancy rates. Researchers at institutions including the University of Nevada, Reno have examined how these variables correlate with volatility spikes in controlled simulations.
Feature engineering transforms raw logs into inputs such as rolling standard deviations of returns and clustering of high-stakes bets. Time-series decomposition separates trend components from seasonal fluctuations tied to peak hours, allowing models to isolate genuine shifts from routine patterns.
Core Algorithms and Their Applications
Recurrent neural networks capture sequential dependencies across consecutive rounds while random forest classifiers rank the importance of individual features like streak length and average bet velocity. Ensemble methods combine outputs from multiple architectures to improve robustness against noisy live streams.
Deployment occurs through edge computing nodes positioned near streaming servers so latency stays under 200 milliseconds. This setup supports live alerts when predicted volatility exceeds thresholds established during model training on historical datasets spanning multiple years.
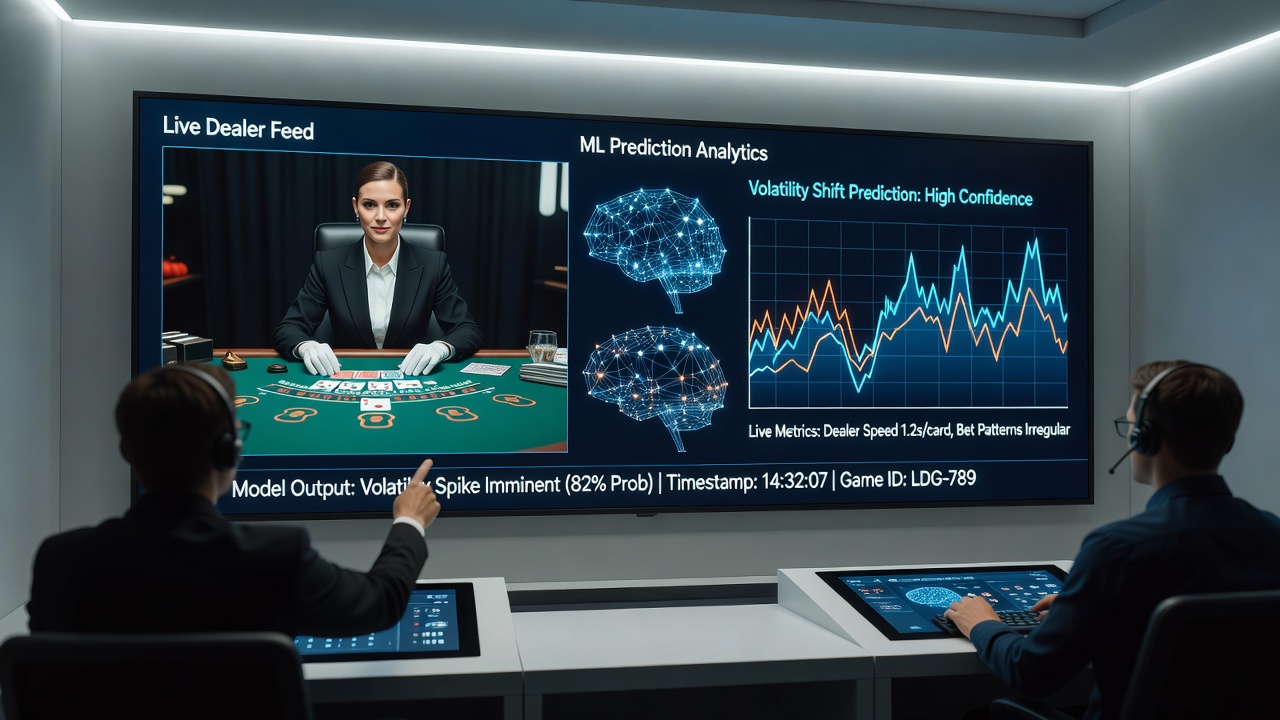
Regional Regulatory Context and July 2026 Developments
Authorities in Nevada and New Jersey maintain reporting standards that encompass algorithmic transparency for systems influencing game integrity. In July 2026 several operators began submitting model validation reports to state gaming boards as part of expanded compliance protocols for digital table offerings.
Australian research groups have published findings on similar applications in electronic table games, noting that gradient descent optimization reduced false positive rates for volatility alerts by 18 percent compared with earlier rule-based systems. These studies draw from anonymized transaction records collected across licensed venues.
Integration Challenges and Technical Constraints
Live video feeds introduce compression artifacts that complicate optical character recognition for card values, requiring additional preprocessing layers before model ingestion. Data imbalance between high-volatility and low-volatility periods demands techniques such as synthetic minority oversampling during training phases.
Model drift occurs when player demographics or rule variations change, prompting periodic retraining cycles. Operators monitor performance metrics including precision-recall curves on holdout sets drawn from recent sessions to maintain accuracy levels above 85 percent in production environments.
Industry Adoption Patterns
European operators licensed under the Malta Gaming Authority have incorporated volatility forecasting into risk management dashboards, linking outputs to dynamic table minimum adjustments. North American platforms report using similar outputs for staffing decisions during anticipated high-variance windows.
Academic partnerships continue to explore reinforcement learning variants that adapt model parameters based on realized outcomes after each shift detection. One project at the Technical University of Denmark demonstrated stable performance across 12-month evaluation windows using online learning frameworks.
Conclusion
Machine learning approaches to volatility prediction in live dealer settings rely on structured data pipelines, validated algorithms, and ongoing regulatory alignment. Continued refinement of these systems depends on access to diverse datasets and cross-jurisdictional collaboration among research teams and operators.